
LTV, LTC, and ARV Explained for Fix and Flip
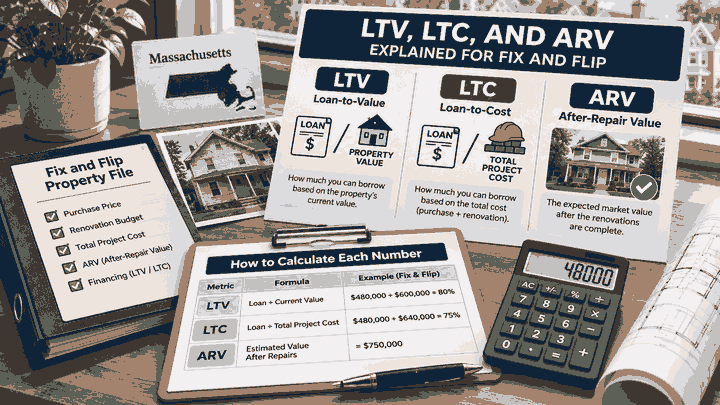
For Massachusetts real estate investors, LTV, LTC, and ARV explained for fix and flip means understanding how a lender evaluates property value, project cost, and the home’s estimated value after renovation.
We provide real estate investment financing in Massachusetts, and we are most experienced in this field. Knowing how these figures work can help you estimate a project’s financing needs before you make an offer.
What do LTV, LTC, and ARV mean?
LTV, or loan to value, compares a loan amount with a property value. Depending on the lender and loan program, the value may be the purchase price, the current as is value, or the estimated value after renovation.
LTC, or loan to cost, compares the loan amount with eligible project costs. A fix and flip project’s cost commonly includes the purchase price and approved renovation budget. Some lenders may include additional eligible costs, so confirm what their calculation includes.
ARV, or after repair value, is the estimated market value of the property after planned renovations are complete. It is a projection supported by comparable renovated properties, the scope of work, and local market conditions.
Some lenders use the term loan to ARV or LTARV for the loan amount divided by the projected after repair value. Others may call that ratio LTV. Ask which property value is used in the calculation.
How to calculate each number
Use these basic formulas to estimate the ratios:
| Metric | Basic calculation | What it helps show |
| LTV | Loan amount ÷ property value × 100 | Loan compared with current or projected property value |
| LTC | Loan amount ÷ eligible project cost × 100 | Share of eligible costs covered by the loan |
| Loan to ARV | Loan amount ÷ estimated after repair value × 100 | Loan compared with the property’s projected finished value |
The formulas are straightforward. The lender’s definitions of property value and eligible project cost determine how useful your estimate will be.
A Massachusetts fix and flip example
Suppose an investor is considering a property with these estimated figures:
| Project item | Amount |
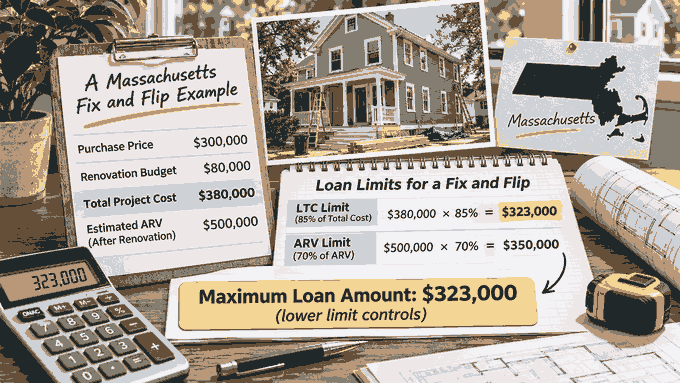
| Purchase price | $300,000 |
| Approved renovation budget | $80,000 |
| Estimated ARV | $500,000 |
| Total purchase and renovation cost | $380,000 |
For illustration, assume a lender considers up to 85 percent LTC and 70 percent of ARV.
The LTC calculation is:
85% × $380,000 = $323,000
The loan to ARV calculation is:
70% × $500,000 = $350,000
If both limits apply, the lower calculation sets the maximum loan amount in this example: $323,000. That equals 64.6 percent of the projected $500,000 ARV.
The investor would need to cover the difference between the project cost and the loan, plus any costs outside the lender’s calculation. Closing costs, lender fees, insurance, taxes, utilities, interest, and reserves may add to the cash requirement. These sample percentages are for explaining the math, not a loan offer or a standard available to every borrower. Lenders can apply different limits and valuation methods.
Why lenders consider all three
Each figure answers a different question.
LTV shows the loan in relation to a property value. If the lender uses the current as is value, it measures the financing against the property before renovations. If the lender uses ARV, it measures the loan against the estimated finished value.
LTC shows how much of the eligible project cost the loan may cover. It can help investors estimate the portion they need to fund themselves.
ARV helps frame the expected value after the work. A well supported ARV can help a lender assess the project and can help an investor compare the acquisition and renovation plan with a potential resale or refinance.
Lenders may use multiple limits at once and size the loan using the lowest result. A published maximum is a ceiling for a qualifying transaction, rather than a promise that every project will receive that amount.
How to estimate ARV for a Massachusetts property
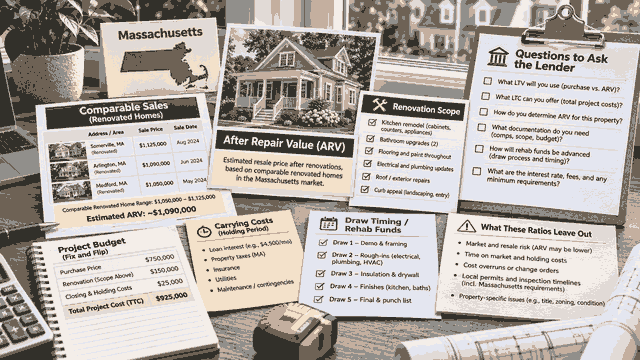
Start with recently sold properties that are similar to the finished project. Look for comparable homes in the same area with a similar property type, size, bedroom count, condition, and renovation quality.
For a Massachusetts investment property, the most relevant comparisons may be nearby renovated homes with similar features. A renovated multifamily property, for example, should be compared with properties that reflect its unit count, layout, and local buyer market. Adjustments may be needed when the comps differ in size, amenities, or condition.
A lender may request an appraisal, broker price opinion, comparable sales, renovation plans, or other valuation support. Build the ARV estimate around evidence from the local market and a defined scope of work.
What LTV, LTC, and ARV leave out
These ratios help explain loan sizing, but they do not show the complete project budget or the investor’s full cash needs. Review the treatment of renovation draws, interest, origination charges, title and legal costs, insurance, property taxes, utilities, sale costs, and contingency funds.
Renovation funds may be released in stages as work is completed and inspected. If the investor pays a contractor before receiving a draw, that timing can affect how much working capital the project needs.
Ask the lender how draw requests work, which documents are required, and how long review and disbursement typically take. Massachusetts fix and flip guides also emphasize renovation budgets, draw procedures, and project cash requirements alongside leverage ratios.
Questions to ask a fix and flip lender
Before comparing financing, ask:
- Does LTV use the purchase price, as is value, or ARV?
- Does the lender calculate a separate loan to ARV limit?
- Which costs count toward LTC?
- How much of the renovation budget may be financed?
- When are rehab funds released, and what documentation is needed?
- Which fees and carrying costs should be included in the project budget?
- What repayment plan and loan term should the project be built around?
Clear answers make it easier to compare the complete loan structure and estimate how much capital the project requires.
Related: Purchase and Rehab Loan Draw Process in Massachusetts
Frequently asked questions
There is no single LTC that works for every project. The available amount depends on the lender’s program, property, borrower, renovation plan, and other loan limits. Compare the approved loan amount with the full project budget.
The terms can be used differently. LTV may refer to a loan compared with current property value, while loan to ARV compares it with the property’s projected value after renovation. Ask the lender which value is being used.
ARV can be one limit in the loan calculation. A lender may also apply LTC, current value, borrower, or project requirements. When multiple limits apply, the lowest calculated amount may control.
Estimate the project cost, subtract the loan amount, and add costs that the loan does not cover. Those may include closing expenses, lender fees, interest, insurance, taxes, utilities, draw timing, and reserves.
ARV means after repair value. It is the estimated market value of a property after the planned renovation is complete, supported by relevant comparable sales and the project scope.